Basic 1
Typically for this person:
- Closer to retiring
- Wants to avoid loss as much as possible
- Investing over the short term (0-2y)
Equities
Other
Other
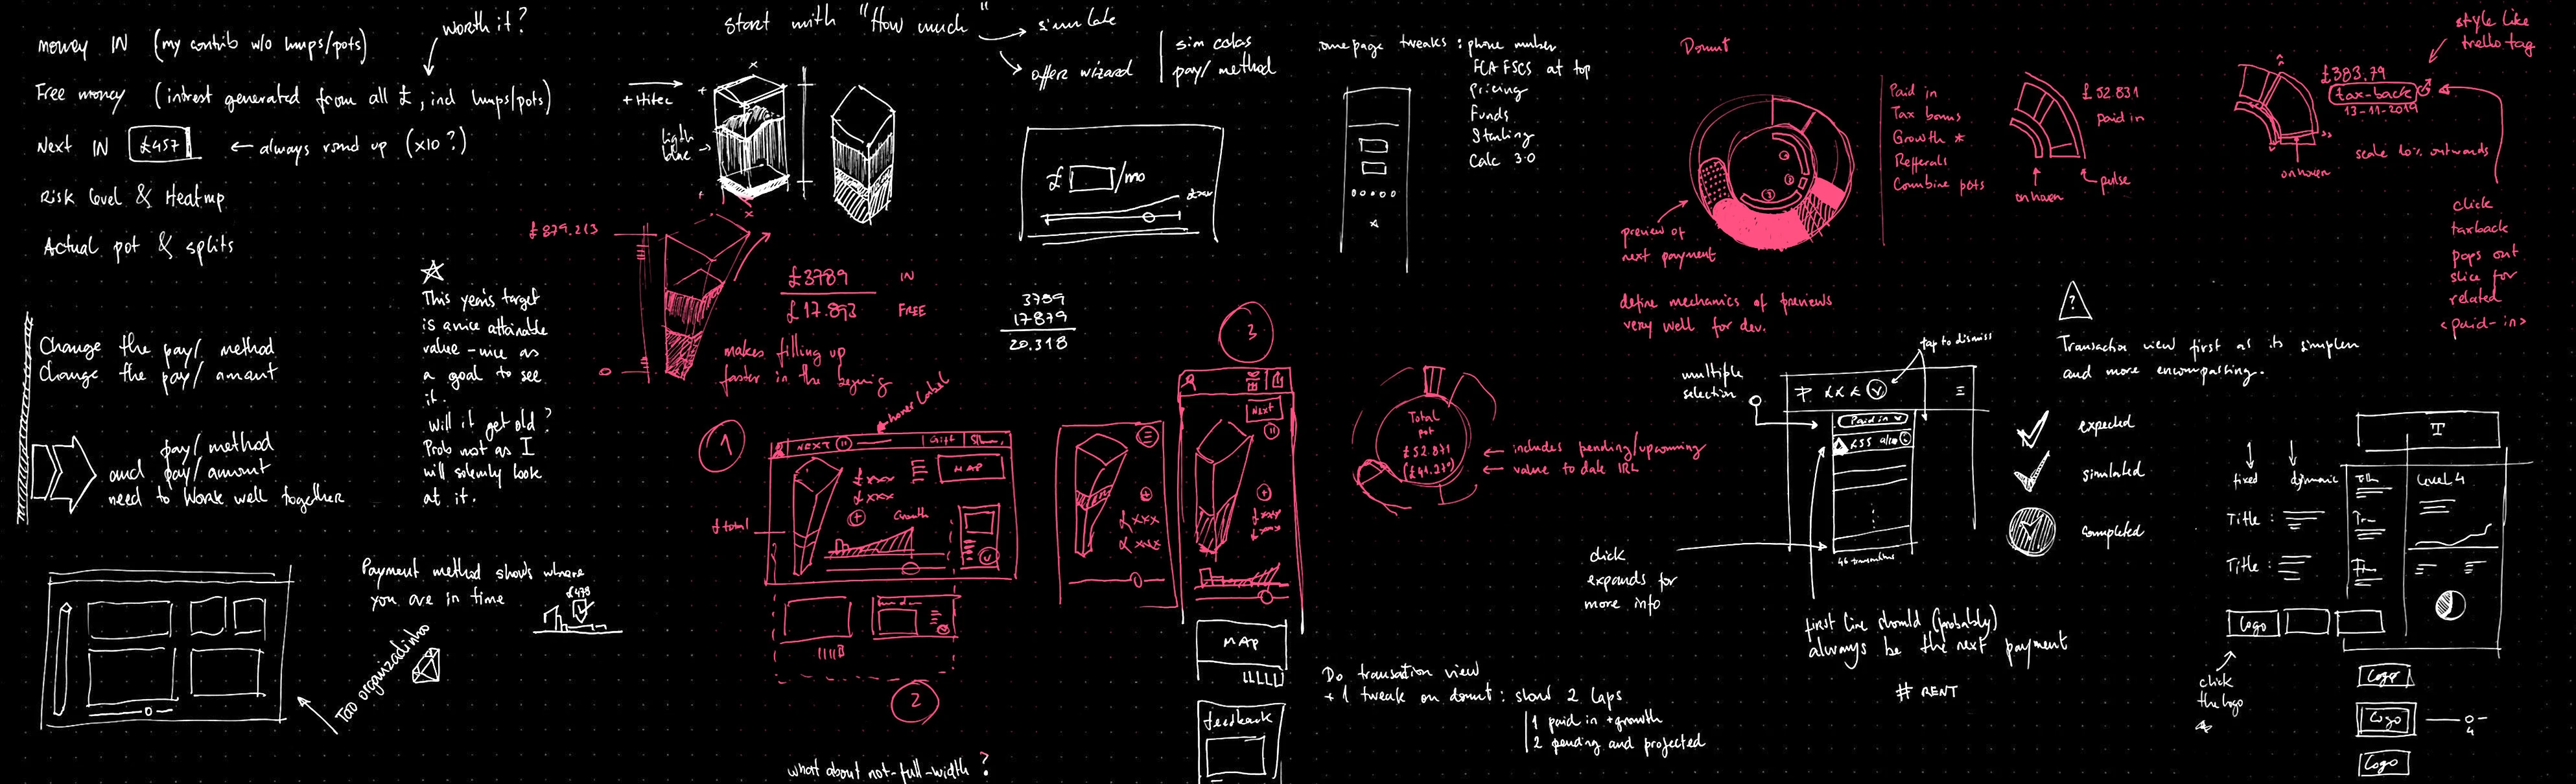
First hire. Shipped an ugly, slow, and cumbersome first version within 7 days. And in less than a year, iterated our way into 3,000 savers and £4M under management.
If I had had more time, I’d’ve made a shorter onboarding. But I joined 7 days from a funding deadline that needed a live product with real customers. And I knew nothing about pensions.
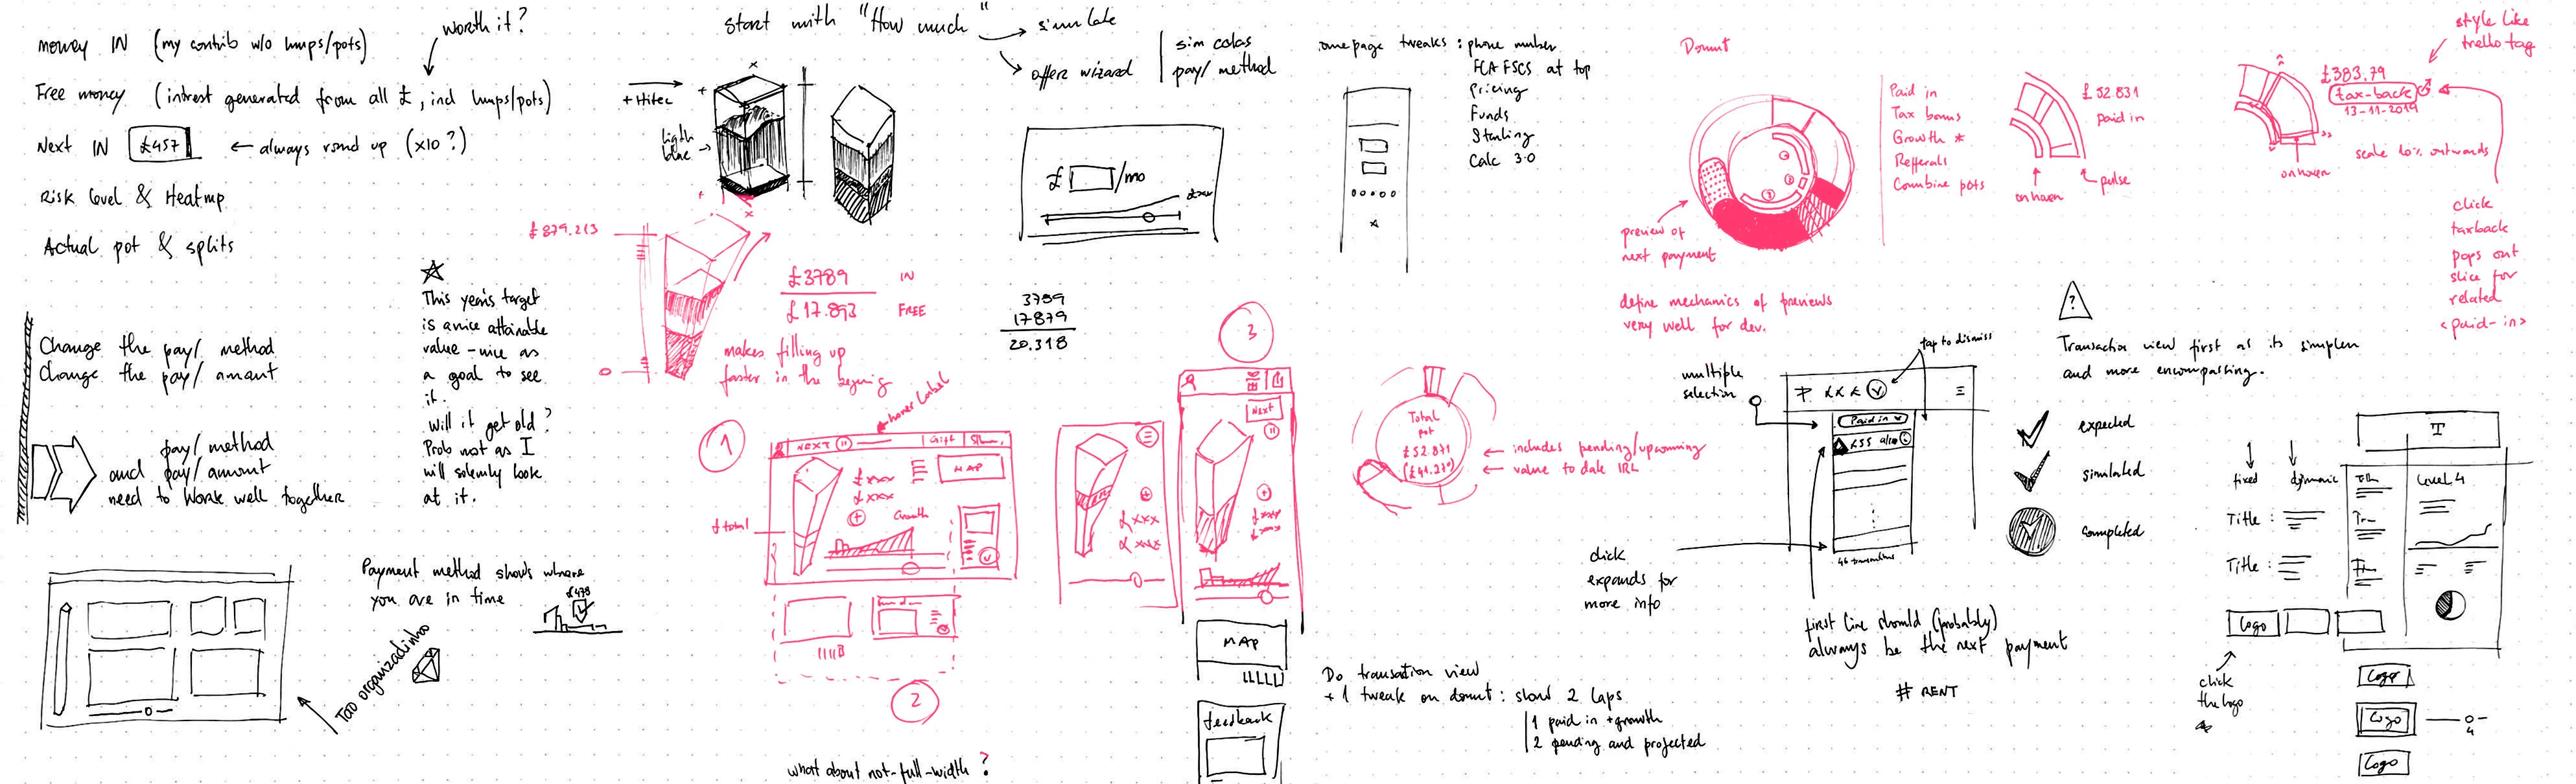
I had to work fast.
First, tell us a couple things about you so we can crunch the numbers
Could you live on £8,767 a year 😐? That’s currently the maximum amount the government gives you in the state pension after reaching retirement age, which for you would be 68. The amount could be less if you haven’t been paying in national insurance all your life.
Most people think that’s not enough so need another source of income after they stop work. The most common and tax efficient way to do this is usually though a pension.
After you turn 55, you can convert whatever you have put aside in a pension during your working years into an annual income for the rest of your life. It could make all the difference in how you spend over a third of your lifetime!
The government thinks pensions are great too, so most of the time when you pay in, they top it up with more free money based on how much tax you pay. We’ve worked out how much you could get based on what you earn.
See how much free money you could get for each payment in 🎉
You won’t get these government top-ups if you pay in more than everything you earned in a year, or more than £40,000. Tax benefits like this do depend on your individual circumstances and might change in the future. If you are a higher rate tax payer your basic rate tax is added by the pension provider, but you have to claim the higher rate tax back on your tax return and then add this to your pension.
Imagine you invite a friend to a party, and they invite two friends, and they invite two friends, and so on, and so on. Pretty soon 300 people are trashing your front room 😰.
This is called “compounding”, and Einstein called it the most powerful force in the universe! This is what should happen to your money over a long time if you leave it in a pension. It’s such a big deal that we’ve given it a new name, Einstein Money.
The main thing about Einstein Money is the younger you start saving, the more you’re likely to get. See how much you might end up with in your pension pot from putting aside that £309, depending on how old you were when you paid in.
Calculation based on your age, the current state retirement age and a growth rate of 5%. Einstein Money is not guaranteed, but is a reasonable estimate of the effect of compound investment returns on the amount you put aside in a pension over a long period of time, using a widely used growth assumption.
With pensions, as with all investments, your capital is at risk and the value of your pension with Penfold may go up as well as down. You may get back less than you put in.
Please use YYYY-MM-DD format
I know how much I want to save each month, just get me going.
I have no idea what I’m doing. Help me decide!
First, roughly how much do you earn?
We think you might need £2,792? per month after you retire. Select the amount that works for you.
This means you might need this much saved up when you retire. Why?
How much do you think you have already?
To reach your goal of £830,820, the best way is to save 31.5% of what you earn, or £1,049 per month?.
From what you’ve said you can save today but remember, the more you save today the less you might pay overall to reach your target.
Based on what you told us you can afford today, here’s how much your savings might need to increase over the next few years to get on track with your goal, assuming your earnings and savings amount both grow with inflation (around 2.3% per year).
The above is just an illustration for how your payments might increase over time to reach your goal. Each year we will help you set a new target based on how much you’ve saved, how much you earn and other factors.
Calculations are based on a set of widely used assumptions.
Our pension plans are managed by the largest money managers in the world. They work hard to protect and build your pot by investing it around the world, keeping costs as low as possible.
You have a few options for how your money will be managed, so please pick which one works for you. Each one is protected by FSCS* and you are free to switch between plans any time at all.
Low cost plans with a range of options based on how much risk you want to take
Total annual fee
0.80%
Cutting-edge plans with a range of options and an added layer of protection
Total annual fee
0.75%
Like our Advanced plan but adapted to make a positive impact on the world
Total annual fee
TBC
Each of our plans has options for how much ‘risk’ you want to take. Basically, higher risk means your pot potentially making more Einstein Money over the long term, but with more ups and downs along the way. Low risk might mean nice and steady growth with fewer bumps but possibly less money overall.
We let you stay in total control of your money by picking which risk level works best for you. Usually, people with several decades until retirement pick a higher risk rating, then switch to a lower rating when they get closer to stopping work. See our FAQ on risk for more information.
Pick which one you think would be best for you based on the below guidance. You can switch anytime.
Typically for this person:
Typically for this person:
Typically for this person:
Typically for this person:
Typically for this person:
Please remember that Penfold does not provide investment advice or personal recommendations, nor any management of the underlying portfolios, and is therefore not required to assess the suitability of these investments for you.
However, these funds are all low cost, highly diversified and widely used by other retail investors like you for long term investing.
Before we continue we need you to understand 3 things:
In short, you could get back less than you invested. Neither we nor the money manager nor anyone else can remove this risk completely. The money manager’s goal is to reduce the chance of this happening and appropriately compensate you for the level of risk you are taking by keeping your costs low, diversifying your investments so you aren’t affected by a specific company or market event and allocating you to the right mix of types of investment.
There is a possibility that currency fluctuations will negatively affect the value of your investments, although the money manager works hard to reduce the impact of this.
Early and unforeseen withdrawals could reduce the amount your money grows. Generally the longer you hold an investment, the more opportunity there is for it to grow in value. Remaining focused on the long-term avoids being penalised by negative short and medium term market moves. You should have a long time horizon. It is generally a good idea to choose a lower risk level as you get closer to the time you can withdraw your money, to reduce the chance of short term drops in value affecting the size of your pot.
*Your investments are covered by the government’s Financial Services Compensation Scheme up to a limit of £85,000. Please be aware that this does not cover a fall in the value of your investment.
Are you a tax resident of only the United Kingdom?
Or manually enter below
We need this to claim your free money from the government.
Make sure to only enter the account details that your payments will come from.
Bank Account Type
If you’re not sure please check this article or speak to us via Live Chat
Penfold’s role is to arrange your pension for you. This means everything from explaining what you need to know about pensions, helping you open one, helping you decide how much to save, and providing a range of features that help you manage your pension in the best way possible over your lifetime. It also means bringing together all the partners that make your pension work behind the scenes.
Please read and accept our terms and conditions document below which outlines in more detail our service and how this interacts with our partners. Please remember though Penfold should always be your first (and only) port of call for anything that you would like to do with your pension.
Penfold Terms and Conditions Penfold Charges Guideper month
(you can change this later)
of the month
Please open your banking app or online portal and use the below details to set up your payment. Once we receive the money you will see it in your Pension Account.
Make sure to use the account you signed up with and add the payment reference below otherwise we’ll have to return it and start again 😅
Your Payment
£2001st of the month
Remember, you can pause or change your payment at any time
Any questions, please don’t hesitate to ask us via Live Chat.
You have successfully opened your Penfold Pension.
We’re expecting your first standing order payment on the 1st of August. We will email you your welcome pack in a couple of days.
Our Mission – We Need You
We’re on a mission to completely re-think pensions and make them work for everyone, but we need your help. We would love to hear your feedback along the way on what we’re doing well or not so well.
Please get in touch via Live Chat and join our Community to let us know what would make the perfect pension for you.
We made the deadline. The flow was 10 pages and 33 steps long, took more than 15 minutes to finish, and needed up to 6 days to set up a pension.
Funding secured.
The long onboarding secured a win, but bled users from day one. Drop-off was around 80%, which hurt acquisition and growth, metrics our investors paid close attention to. However, I had anticipated this and was already working on improvements.
Set aside some money for your pension, as a percentage of your salary or just type in a number if you already know how much you want to save.
Decide how much to save.
Based your current monthly earning and a set of widely used assumptions, this is how much you’d need as a monthly pay from your pension to stop working confortably. Feel free to play around with that value.
Top get that much out of your pension, this is how much you should save each month now.
How much should you save?
£1,000
Your monthly earnings
96%
-
+
Set aside a percentage of your salary
£959
Save monthly into my pension
Save
Simplify!
£3,908
This is how much you’ll get from your pension, higher is better, lower is easier. If you’re unsure leave it as is. The less you put aside now, the steemper the ramp up.
Pension pay out
£10
£290
£423
£541
£601
£669 pay in
2019
2020
2021
2022
2023
2024
…
…
2045
2054
5
10
15
Max
Years ramping up
Salary %
Save
There’s 3 main things we need you to be aware of, and accept:
Risk acceptance
Capital is at risk
Exchange rates affect growth
Early withdrawls impact returns
I understand and accept these risks.
Select risk level
Your savings will be managed by Blackrock, the world's largest asset manager. They make your money work for you by investing it around the world, with FSCS protection.
Annual fee
0.75%
· Slow and steady growth
· Less prone to ups and downs
· Best if closer to retiring (<10yrs)
Bonds | 63%
Stocks | 37%
Select
Level 1
i
Higher risk
Typically
higher rewards
Lower risk
Typically
lower rewards
Save
These include both general Penfold terms and conditions, as well as our partners’.
At the moment we are only able to offer a Penfold pension to those who have a UK tax residency. This is because you need to be subject to tax in the UK to qualify for the government top ups into your pension.
By proceeding you confirm you are a UK Tax Resident.
Terms and Conditions
Penfold Terms
Scheme Administrator Terms
Key Features Document
Member Declaration
UK Tax Residency
I understand and accept all of the above.
Penfold and Gaudi intend to move the Penfold Pension to a new registered pension scheme in due course, with no additional cost or charge to you.
By accepting these terms you acknowledge the above and note that:
On and from the date we give you notice that the transfer of your interests in the Penfold Pension under the Scheme to an arrangement for you under another registered pension scheme selected by us will happen, you hereby authorise and instruct Penfold and Gaudi to transfer your contributions to and Investments in the Penfold Pension held at that date, and apply any cash or investment received in your Penfold Pension after that date to the arrangement under the registered pension scheme selected by us for your benefit, along
with all your information and transaction history held under your Penfold Pension to that new registered pension scheme all as more particularly described in the notice that will be given by us to you telling you of that move.
Important notice
If unsure please check this article.
Country of birth
Salutation
Legal gender
Citizenship
Main source of income
AA000000A
National Insurance number
Legal
First name
Last name
Phone number
dd-mm-yyyy
Date of birth
currentuser@domain.com
Email (login)
****************
Password
Change password.
Main
Enter postcode to lookup
Postcode lookup
Address line 1
Address line 2
Town/City
County
House number
Address
Set up your Direct Debit
Please confirm your regular payment details below. Remember, you always
have absolute flexibility with Penfold, so you can pause or change payments at
any time via your account page.
£367
per month
(you can change this later)
15th
of the month
If you choose a date within the next 8 days your first payment may not be taken
until the following month.
Bank details
Account Number
Sort Code
12345678
00 - 00 - 00
Make sure to only enter the account details that your payments will come from.
Bank Account Type
Personal
Business
The Direct Debit
Guarantee

The Guarantee is offered by all banks and building societies that accept instructions to
pay Direct Debits
If there are any changes to the amount, date or frequency of your Direct Debit Penfold
will notify you (normally 10 working days) in advance of your account being debited or
as otherwise agreed. If you request Penfold to collect a payment, confirmation of the
amount and date will be given to you at the time of the request
If an error is made in the payment of your Direct Debit, by Penfold or your bank or
building society, you are entitled to a full and immediate refund of the amount paid
from your bank or building society
If you receive a refund you are not entitled to, you must pay it back when Penfold asks
you to
You can cancel a Direct Debit at any time by simply contacting your bank or building
society. Written confirmation may be required. Please also notify the organisation.
I have read and accept this Direct Debit Mandate.
Please note our business partner Seccl Custody Limited (Service user
number 184278) is the one who actually holds all customer money in a
safeguarded separate bank account — so their name will appear on your bank
statement.
Please also read this notice in relation to your clawback rights.
Set up Direct Debit
You’re all set
You have successfully opened your Penfold Pension.
We’re expecting your first direct debit payment on the 15th of November.
We will email you your welcome pack in a couple of days.
Go to your account
Our Mission – We Need You
We’re on a mission to completely re-think pensions and make them work for
everyone, but we need your help. We would love to hear your feedback along
the way on what we’re doing well or not so well.
Please get in touch via Live Chat and join our Community to let us know what
would make the perfect pension for you.
Making it modular required us to change our data model. Accounts assumed one or more pensions, so zero didn’t work and our initial flow couldn’t save progress, as there wasn’t an account yet. Fixing that allowed users to complete modules individually and finish onboarding at their convenience.
Save
There’s 3 main things we need you to be aware of, and accept:
Risk acceptance
Capital is at risk
Exchange rates affect growth
Early withdrawls impact returns
I understand and accept these risks.
Select risk level
Your savings will be managed by Blackrock, the world's largest asset manager. They make your money work for you by investing it around the world, with FSCS protection.
Annual fee
0.75%
· Slow and steady growth
· Less prone to ups and downs
· Best if closer to retiring (<10yrs)
Bonds | 63%
Stocks | 37%
Select
Level 1
i
Higher risk
Typically
higher rewards
Lower risk
Typically
lower rewards
Annual fee
0.75%
Your savings will be managed by Blackrock, the world's largest asset manager. They make your money work for you by investing it around the world, with FSCS protection.
Select risk level
Higher risk
Typically
higher rewards
Lower risk
Typically
lower rewards
I understand and accept these risks.
There’s 3 things we need to highligth
Capital is at risk
Exchange rates affect growth
Early withdrawls impact returns
Risk acceptance
Save
Select
Selected
Bonds | 63%
Stocks | 37%
· Slow and steady growth
· Less prone to ups and downs
· Best if closer to retiring (<10yrs)
Level 1
i
Select
Bonds | 44%
Stocks | 56%
· More growth potential
· Some ups and downs
· Midway from retirement (10-15yrs)
Level 2
i
Select
Bonds | 28%
Stocks | 72%
· Significant growth potential
· Significant ups and downs
· Long way to retirement (15 yrs+)
Level 3
i
Select
Selected
Bonds | 14%
Stocks | 86%
· Highest growth potential
· Large ups and downs
· Far from retirement (15 yrs+)
Level 4
i
Back
Invest
getpenfold.com
8:24
Yearly progress
Jul ‘19 — Jun ‘20
Paid in
£1,350
Yearly goal
£1,600
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Basic 1
Investment fund
£422 on 2nd
Next payment
Referral
Top up
Combine
Yearly goal
Jul ‘19 — Jun ‘20
Basic 1
Investment fund
£422 on 2nd
Next payment
Combine
Top up
Referral
Paid in
£1,350
Yearly goal
£1,600
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Gain/Loss:
+£0.00
+0.00%
Pot:
£0.00
getpenfold.com
8:24
One developer meant one platform, and I argued a mobile-only pension would look less serious, favoring desktop, but the live data would quickly disagree. With a few tweaks to the components, I made a mobile flow that gave us the desktop one for free. And free we could handle.
Signup was now just a few minutes. But creating the pension required a final step that could take up to 6 days. Better than the banks, but an eternity by any other standard. And the problem was a bank and two other parties, none of which shared our enthusiasm for speed.
Bad.
Much worse.
No relief.
userIDcustodianIDoperatorIDbankIDpensionLegally and technically, this was peak efficiency, taking up to a meager 144 hours to complete. It was also textbook region-beta paradox: a bad process gets tolerated, but this I had to crack.
userID, 2 temporaryIDs, and the pensionuserID and the temporaryIDscustodianID, operatorID, and bankIDWith some prodding, I learned their ID checks were manual, and if found, an incorrect ID could simply be overridden with a new one without consequence. It got me thinking: if we created a couple of temporary IDs, tracked them, and then replaced them accordingly, we’d have instant pensions, a first in our industry.
Built, tested, and launched that afternoon.
Sign up
user@domain.com
***********************
Password
Sign up for free
I’ve read and accept Penfold’s
privacy policy.
Log in instead
Open your pension in minutes.
getpenfold.com
8:24
home
Welcome
Three small steps to begin saving.
First, choose how your money will be managed.
Initial setup is
25% complete
Set up
Investment fund
Set up
Personal information
Set up
Payment details
Referral
getpenfold.com
8:24
Annual fee
0.75%
Your savings will be managed by Blackrock, the world's largest asset manager. They make your money work for you by investing it around the world, with FSCS protection.
Select risk level
Higher risk
Typically
higher rewards
Lower risk
Typically
lower rewards
I understand and accept these risks.
There’s 3 things we need to highligth
Capital is at risk
Exchange rates affect growth
Early withdrawls impact returns
Risk acceptance
Save
Select
Selected
Bonds | 63%
Stocks | 37%
· Slow and steady growth
· Less prone to ups and downs
· Best if closer to retiring (<10yrs)
Level 1
i
Select
Bonds | 44%
Stocks | 56%
· More growth potential
· Some ups and downs
· Midway from retirement (10-15yrs)
Level 2
i
Select
Bonds | 28%
Stocks | 72%
· Significant growth potential
· Significant ups and downs
· Long way to retirement (15 yrs+)
Level 3
i
Select
Selected
Bonds | 14%
Stocks | 86%
· Highest growth potential
· Large ups and downs
· Far from retirement (15 yrs+)
Level 4
i
Back
Invest
getpenfold.com
8:24
Welcome
Initial setup is
75% complete
Great. Final step is to add some money into your account.
Complete
Investment fund
Complete
Personal information
Set up
Payment details
Referral
getpenfold.com
8:24
Yearly goal
Jul ‘19 — Jun ‘20
Basic 1
Investment fund
£422 on 2nd
Next payment
Combine
Top up
Referral
Paid in
£1,350
Yearly goal
£1,600
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Gain/Loss:
+£0.00
+0.00%
Pot:
£0.00
getpenfold.com
8:24
Onboarding was fast, and the major leaks patched. So I turned to the quieter work: single-digit gains, and finding several of them. Tuning the engine that grows the product: reliable, repeatable. Unremarkable work, executed remarkably.
We checked the funnel daily, and every drop was discussed at the morning stand-up. I followed up with FullStory, rage clicks and coffee.
Every Friday, Support and I, and the occasional guest user, went through the week’s top complaints and requests, setting up the week ahead.
Some users are very keen to try new stuff, and eager to give feedback. I started the programme to make it easier for their voices to be heard.
When we shipped what a user had asked for, I thanked them personally. We also set up an auto-reply for every fix on a reported bug or feature.
Full name
Date of birth
Relation to you
I've read and accept the nomination declaration.
Nominate
Nominate beneficiary
i
What’s a Beneficiary, and why should I nominate one?
Beneficiary
Back
getpenfold.com
8:24
Nominate
I've read and accept the nomination declaration.
John Smith
13-11-1946
Legal guardian
Nominate beneficiary
i
What’s a Beneficiary, and why should I nominate one?
Beneficiary
Back
getpenfold.com
8:24
Nominate beneficiary
Thank you for nominating a beneficiary.
We’re updating our records and will provide confirmation once we’re done.
John Smith
13-11-1946
Legal guardian
Dismiss
Success
Beneficiary
Back
getpenfold.com
8:24
“But what if I die?”
That’s how Joe T. wrapped a Friday guest session. And after a chuckle, it got me thinking: what if? So after the meeting, I asked Customer Support to call our partners and find out. Turns out it was a manual process (surprise!) and all we needed were a few inputs. So I put up a single screen, built entirely from existing components, and challenged the engineers to ship it before drinks that afternoon.
From request in the morning, to shipped in the afternoon, to us thanking Joe from the pub!
So if it was all working, why the stale growth?
For months we tried to educate the unpensioned market, specifically the self-employed. But it looked like they simply didn’t care. And with no clear holes in the product that would otherwise hurt traction, I suggested we target those who’d proven they cared, by already having a pension. The pensioned.
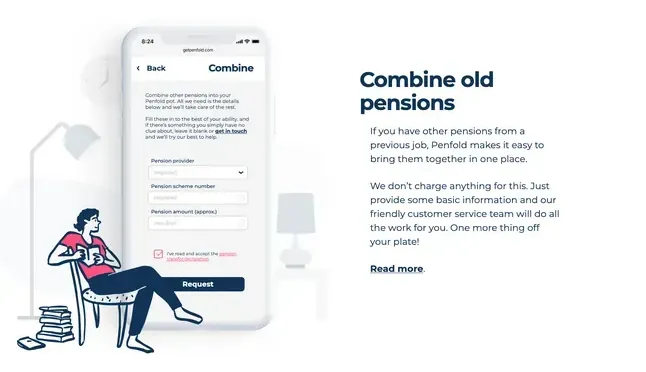
Combine, the way by which a pension is transferred from one provider to another and combined with the existing pension, was dead last on our website. The whole structure and look were already a bit stiff, so we just redesigned the whole thing. Bumping Combine to the third section, following ease of use.
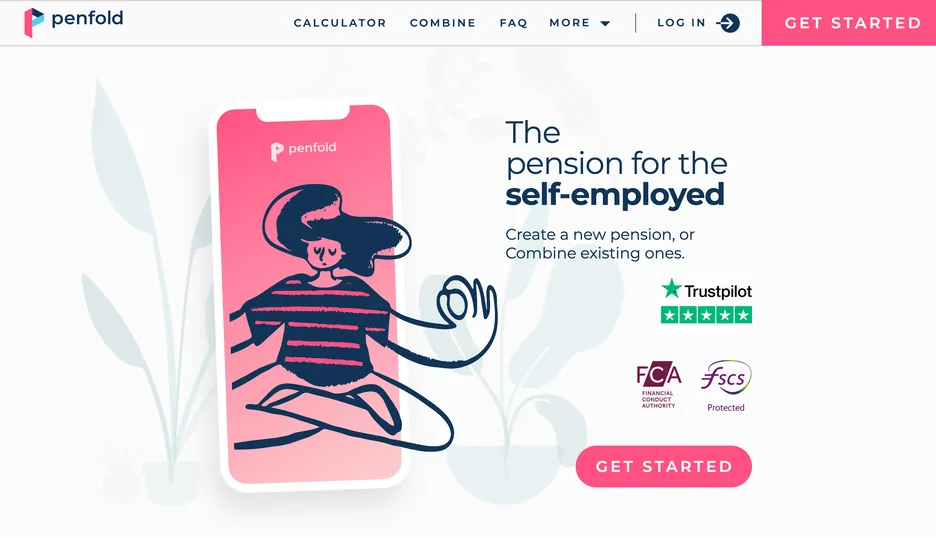 Tag: Create a new pension, or Combine existing ones.
 Redesign
 3rd section from top: promoted 6 spotsCombine section
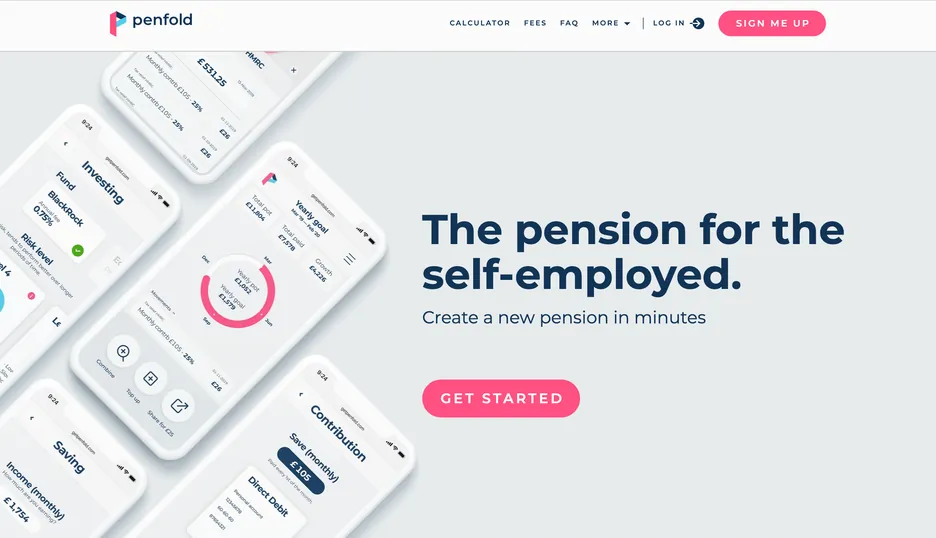 Tag: Create a new pension in minutes
 Previously
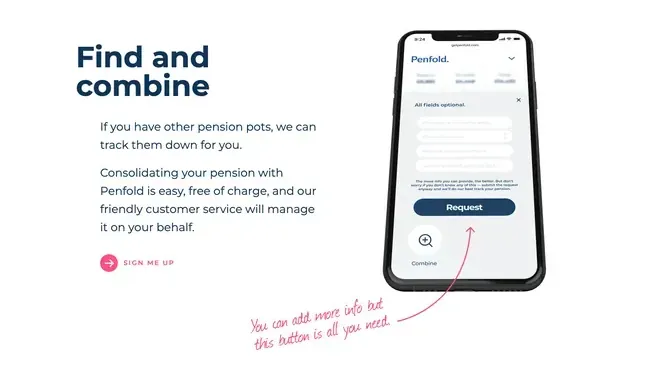 9th section from topCombine section
The new targeting jolted our Combine feature to the top of my priority list, essentially becoming the product’s flagship overnight. This meant any minor improvement had a disproportionate effect on our growth. So we shipped every little refinement as it was ready.
We’ll search and combine all your pensions for you.
Provide whatever info you can, or submit a blank request. We’ll get in touch if we need anything else.
Request
Employer’s name/company
Pension provider
Pension policy number
Current pension amount (est.)
Back
Combine
getpenfold.com
8:24
If you are unsure about any of these fields, fill in as best as you can. If there’s something you simply can’t find, get in touch and we’ll try our best to help.
Combine
Combine other pensions into your Penfold pot. All we need is the details below and we’ll take care of the rest.
required
i
Pension amount (aprox.)
required
i
Pension scheme number
required
i
Pension provider
required
i
Pension provider’s address
Reference list pension providers here.
Pension eligibility
Combine
Back
getpenfold.com
8:24
Combine
Combine other pensions into your Penfold pot. All we need is the details below and we’ll take care of the rest.
Fill these in to the best of your ability, and if there’s something you simply have no clue about, get in touch and we’ll try our best to help.
required
Pension provider
required
i
Pension scheme number
required
i
Pension amount (approx.)
I’ve read and accept the pension transfer declaration.
Combine
Back
getpenfold.com
8:24
If you are unsure as to any of these fields, please fill in as best as you can, and if there’s something you simply can’t find, get in touch as we’ll try our best to help.
Combine
Please fill in the details regarding any pension you want to combine into your Penfold pot. You can submit as many combine requests as you want.
McDonalds
Employer
Aviva
Pension provider
PFL2918811
Pension scheme number
?
£4,299
Pension amount (aprox.)
?
Combine
Back
getpenfold.com
8:24
Pension amount (aprox.)
This can be a super rough estimate (+/- £5,000).
This should be stated on recent documentation from your provider, also referred to as 'transfer value' or 'approximate value'. Or you could look it up online if you have access, or call them and ask.
If you cannot locate this number, a good rough estimate is multiplying £500 by the amount of years you worked for that employer.
Dismiss
If you are unsure as to any of these fields, please fill in as best as you can, and if there’s something you simply can’t find, get in touch as we’ll try our best to help.
Combine
Please fill in the details regarding any pension you want to combine into your Penfold pot. You can submit as many combine requests as you want.
McDonalds
Employer
Aviva
Pension provider
PFL2918811
Pension scheme number
?
£4,299
Pension amount (aprox.)
?
Combine
Back
getpenfold.com
8:24
Dismiss
Combine another?
Success
Your request has been submitted. We’ll notify you once it’s processed successfully, and display it on your transactions list.
Aviva
Pension provider
PFL2918811
Pension scheme number
£4,299
Pension amount (approx.)
Combine
Done
getpenfold.com
8:24
Growth finally caught up with the product, as the new strategy yielded 6x the signups.
Set up your pension
3 simple steps and you’re saving!
user@domain.com
***********************
Password
I’ve read and accept Penfold’s
privacy policy.
Create account
getpenfold.com
8:24
Getting started
You’re a few simple steps away from having your pension setup.
First step is choosing a growth profile. This defines how your pension is invested and its potential for growth over time.
Start
How much to save?
What you save today directly impacts what you’ll get later. If you’re unsure about the amount: Estimate👇
Estimate
Welcome
getpenfold.com
8:24
Final step
All that’s left to do is start putting some money into your pension.
You can start with a simple one-off top-up or set a regular recurring contribution.
Finish
Current estimate
Save now:
Projected pot:
Estimated growth:
£ 250
£ 241.357,87
£ 123.478,62
Change
Welcome
getpenfold.com
8:24
Yearly goal
Jul ‘19 — Jun ‘20
Basic 1
Investment fund
£422 on 2nd
Next payment
Combine
Top up
Referral
Paid in
£1,350
Yearly goal
£1,600
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Gain/Loss:
+£0.00
+0.00%
Pot:
£0.00
getpenfold.com
8:24
For months the market challenged us, and we challenged everything else, be it the speed at which partners moved, or how much our audience actually cared about our product. We held our resolve to keep failing until we didn’t, and an unwavering focus on the only non-negotiable: the excellence with which we served our users. To this day, Penfold is the best working experience I’ve had, and a true 0 → 1 that I’m tremendously proud of.
Set up your pension
3 simple steps and you’re saving!
user@domain.com
***********************
Password
I’ve read and accept Penfold’s
privacy policy.
Create account
getpenfold.com
8:24
Getting started
You’re a few simple steps away from having your pension setup.
First step is choosing a growth profile. This defines how your pension is invested and its potential for growth over time.
Start
How much to save?
What you save today directly impacts what you’ll get later. If you’re unsure about the amount: Estimate👇
Estimate
Welcome
getpenfold.com
8:24
Fund selection
Level 1
Payment details
£422 on 2nd
First payment should leave your bank around <9th March> and will be in your pension around <11th March>.
Yearly goal
Jul ‘19 — Jun ‘20
£2,600
72% complete
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Paid in
£1,350
+Upcoming
£1,600
Combine
Top up
Share for £25
Total pot
£5,392
Growth
£529
+5.23%
getpenfold.com
8:24
Fund selection
Level 1
Payment details
Paused
Your contributions are currently Paused.
Yearly goal
Jul ‘19 — Jun ‘20
£2,600
72% complete
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Paid in
£1,350
+Upcoming
£1,600
Combine
Top up
Share for £25
Total pot
£5,392
Growth
£529
+5.23%
getpenfold.com
8:24
Fund selection
Level 1
Payment details
£422 on 2nd
Yearly goal
Jul ‘19 — Jun ‘20
£2,600
72% complete
Jul ‘19
Jan ‘20
Oct
2019
Apr
2020
Paid in
£1,350
+Upcoming
£1,600
Combine
Top up
Share for £25
Pause contributions
Please confirm you want to pause contributing into your pension.
Recurring
£250
Paid on
1st
Recurring
£250
Paid on
Paused
Your contributions will be paused after your next payment on dd-mm.
Confirm
Total pot
£5,392
Growth
£529
+5.23%
getpenfold.com
8:24
Dismiss
Combine another?
Success
Your request has been submitted. We’ll notify you once it’s processed successfully, and display it on your transactions list.
Aviva
Pension provider
PFL2918811
Pension scheme number
£4,299
Pension amount (approx.)
Combine
Done
getpenfold.com
8:24
Combine
Top up
Share for £25
Paid in
expected 01-02-2020
£2,000
jonhsmith
processing
£25
Paid in
01-01-2020
£2,001
Tax bonus
08-02-2020
46
Funding Circle
processing
£5,000
Catapult (17-19)
23-12-2019
£5,123
kinkybits78
12-01-2020
£30
Paid in
01-12-2019
£249
£23,392
Lifetime
Yearly
24
Total pot
£109,456
Growth
£5,724
+5.23%
getpenfold.com
8:24
More risk, tends to perform better over longer
periods of time.
Level 1i
· Lower risk
· Slow and steady growth
· Short term investment
Equity | 85% Bonds | 15% Level 2· Lower risk
· Slow and steady growth
· Short term investment
Equity | 85% Bonds | 15%getpenfold.com
8:24
Back
Estimate
23%
£ 250
One off top up
Salary %
1st
Paid on:
Debit details
123456
Account number
12 - 12 - 12
Sort code
Business
account
One off
Your payments are powered by Seccl Custody Limited, which will be the reference name on your bank statements. Their Direct Debit service user number is 184276.
Please also read this notice in relation to your clawback rights.
Save
Pay-in amount
Back
Payment
getpenfold.com
8:24
Nominate
I've read and accept the nomination declaration.
John Smith
13-11-1946
Legal guardian
Nominate beneficiary
i
What’s a Beneficiary, and why should I nominate one?
Beneficiary
Back
getpenfold.com
8:24
Full name
Date of birth
Relation to you
I've read and accept the nomination declaration.
Nominate
Nominated beneficiary
i
What’s a Beneficiary, and why should I nominate one?
What is a beneficiary
A pension is designed to support you and your loved ones for the rest of your life after you stop working. It is therefore likely that you have some money left in your pot when you eventually die.
When this happens, that money is not lost, but can be passed on to whoever you wish - this is known as a beneficiary.
If you die before age 75, the money in your pension will be passed onto your beneficiary free of tax.
If you die after age 75, the beneficiary will pay income tax at their marginal rate on the money that is left.
You can nominate one or more beneficiary, and they can be a person or a legal entity. If you would like to nominate more than one beneficiary or a legal entity please get in touch.
Got it
Beneficiary
Back
getpenfold.com
8:24
Salary based
Save
Total pot: £312,281
Paid in
Growth
87% of ideal pot
£ 2,500
Monthly income
2%
Save as a %
+
-
£ 250
Pay-in amount
One off
Estimate
Back
getpenfold.com
8:24
“Setting up my pension with Penfold took me 5mins.”
Bobby, 14 May 2020
“I’ve put off sorting out my pension for AGES as I always assumed it would be annoying and complicated.”
Kim, 13 May 2020
“I’m a self-employed wedding photographer so I didn’t feel like I fit in properly with other providers.”
Cara, 14 May 2020
“…customer service was not patronising just helpful”
Michelle, 18 May 2020
“Having been trying to set up a pension for ages. This was really easy!”
Bennew05, 22 April 2020
“Super simple and easy to set up”
Caroline, 22 April 2020
“Great App!”
Daniela, 24 April 2020
“Great app, simple, clean and no jargon, easy to understand and says what it does on the tin!”
LMKeys, 24 April 2020
“Super helpful with deciding the right amount to submit monthly”
Kanisha, 1 May 2020
“Great easy to use app, fantastic service”
Ed, 19 May 2020
“So simple”
BPHollins, 4 June 2020
“I’ve never set up a pension before, and this made it a breeze I had my account set up in 5 mins.”
TamIyn, 25 June 2020
Penfold now manages over £1B, and was voted Best Pension 2026.


Ship often.
Make it fast.
Target accordingly.